

The Pain Trade Remains Higher As Hedge Funds Sell Every Rally
After suffering tremendous losses in January and February, March was a very confusing month for hedge funds: as JPMorgan’s Prime Brokerage writes in its monthly note, the start of March was characterized by one of the largest de-grossing episodes among Equity L/S funds in N. America, along with quite significant net selling globally (especially in APAC), and resulted in some marquee names such as Tiger Global suffering massive losses.
So as markets closed out the month and quarter with a very sharp rebound in equities, most funds were again caught by surprise, while few are willing to embrace the recent move higher in risk as a persisting trend.
Commenting on the recent failure of hedge funds to embrace the rally, JPM writes that there are still many concerns to deal with, but the “net selling we’ve seen from HFs into this rebound (4wk global net flows at -2 to -3z) is quite consistent with other market lows (post Dec 2018 and Mar 2020) and may suggest, from a contrarian perspective, that equity markets could continue to grind higher.”
Looking back to the prior episodes, JPM’s John Schlegel writes that while net flows did turn more positive starting about a month after the market lows, “it wasn’t until net flows reached a significantly positive level (i.e. about +2z), the market was back to highs, and average net positioning levels were back above average that the market saw a more meaningful pullback.”
Well, as of this week, the average positioning level was still around -0.7z and gross/net leverage were still below the 20th %-tiles vs. the past year. Thus, from a positioning/flows perspective, the prime desk believes that the “pain trade” is still higher for now and the rally could persist for a bit longer, given the bias to STR (sell-the-rally), positioning still low, and possibly a lack of incrementally negative news (i.e. we “know” Fed is very hawkish, Russia/Ukraine conflict isn’t new, and expectations are that inflation will remain high).
We’ll do a deeper dive of these points shortly, but before we do a quick tangent: according to JPM, one of the recent areas of focus during the 2H Mar rebound has been the outperformance of High short interest stocks. About 6 months ago (in October) the desk outlined 5 reasons why shorts could continue to work in the medium term. Looking back, that trade indeed worked and we’ve seen quite large underperformance of High SI stocks in the past 6 months — the JPM High SI basket has underperformed the SPX by ~35% since the start of Oct 2021, including the recent rebound.
So looking back at the 5 reasons JPM gave 6 months ago, do they still hold today? The short answer is “somewhat.” I.e., the set up doesn’t appear particularly bad for shorts per se, but it also doesn’t look as clear as it did 6 months ago.
- Reasons why shorts could still work, i.e. underperform: ETFs still a high % of the short book, limited recent shorting of High SI stocks, still relatively few stocks with High SI % float (although this has increased from 6 months ago)
- Reasons why shorts might not work as well going forward: Most of the recent covering has been in ETFs (i.e. potential to cover single-names if funds were to continue to cover shorts), short leverage still low, but net leverage also low (i.e. limited need to hedge directional risk), “risky” factors have already underperformed significantly and might not continue to do so going forward.
With that in mind, let’s go back to some of JPM’s core observations starting with…
1. Selling The Rally… Not as Unusual as One Might Think
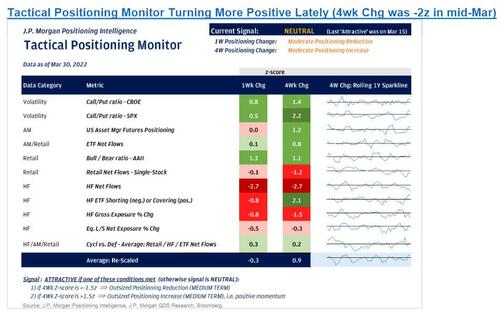
As markets have rallied over the past couple weeks, the biggest driver seems to be a reduction of hedges. When looking at the components of the bank’s Tactical Positioning Monitor (TPM) and comparing current levels to those as of mid- March, volatility related metrics (e.g. call/put ratios), HF ETF shorts/covers, and US Asset Manager Futures positioning have seen the biggest positive change in the 4wk scores (all were about -1z to -2z vs. positive levels most recently).
From a HF flow perspective, however, there’s been a fairly strong bias to sell-the-rally (STR) as JPM Prime has seen net selling in 8 of the past 9 days, during which stocks have staged a torrid rally. That said, this is not that unusual, as markets saw similar biases in the flows post the low in Dec 2018 and Mar 2020.

Looking at these periods more closely, if we were to follow the prior pattern then we should see net flows turn to moderate buying if markets grind higher/sideways starting in a couple weeks (e.g. 4wk net flows were positive in Feb 2019 and May 2020, about 2 months after the low). However, HF net flows didn’t reach a significantly positive level (i.e. around 2z) until 4-5 months after the low. Coincidentally, by this time the market was back near ATHs and positioning levels were above average (nearly +0.5-1z), potentially why those peaks in flows/higher positioning proved to be a good time to tactically short the market. In other words, the moment hedge funds finally rush in, that will be the time to short.
Then again, with positioning levels still quite low vs. the past year (i.e. around -0.7z currently), perhaps it’s too early to expect a sharp pullback. Similarly gross and net leverage for HFs remains relatively low vs. the past year (around 20th %-tile across All Strategies and


Providing a bit more perspective on HF leverage, for the typical fund across strategies, hedge fund net leverage recently fell back to its median levels and gross is below historical median historical levels. This is down quite a bit from where things stood ~6 months ago, indicative of the fairly broad decline in risk levels. That said, exposures are not necessarily at extreme lows on a longer time frame (i.e. past 3-5 years).
As for what is driving the net and gross flows across strategies and regions, the net selling over the past 1-2 weeks is mostly in N. America and EMEA and strongest among Multi-Strats and Quants. L/S funds have been net buyers of N. Am. recently (although sellers of EMEA). From a gross flows perspective, the recent de-grossing is strongest in EMEA and broad-based across strategies, while the opposite is true in APAC. However, on a 20-day basis, the de-grossing among Eq L/S and Quants in N. Am. is largest.

2. Will Shorts Continue to Rip Higher?
One feature of the market bounce since Mar 14 is the outperformance of High Short Interest stocks in N. America, and generally “riskier” stocks / prior laggards. For context, the JPM High SI basket, JPTASHTE, is up 22% since 3/14 (just over 2x the SPX’s gain) and the top 25 most crowded net shorts in N. Am. are up about 20% over the period vs. a gain of only ~11% for the top 25 most crowded net longs. Additionally, the High Vol basket (JP1HVO) is up 31% and the Momentum shorts (JP1SMO & JP16SMO), i.e. laggards over the past 12M or 6M, are up 28-29% over the period.
In early October last year, JPM wrote a note that outlined why shorts could continue to perform well over the medium term (i.e. 6 months). Looking back at what’s transpired, this has played out fairly well, as evidenced by large underperformance of High SI stocks in the past 6 months—the JPM High SI basket, JPTASHTE, has underperformed the SPX by ~35% since the start of Oct 2021.
As a refresher, in early Oct last year, there was concern as to whether the shorts would continue to work since they had performed quite well since the middle of Feb of last year. Generally speaking, there were still concerns about whether retail investors and so-called meme stocks might cause significant pain to shorts. While that was (and still is) a potential risk to specific shorts, it seemed that there was still ample room for shorts to continue to perform relatively well, which they did. So looking back at the 5 reasons JPM gave 6 months ago, do they still hold today? The short answer is “somewhat.” I.e., the set up doesn’t appear particularly bad for shorts per se, but it also doesn’t look as clear as it did 6 months ago.


One last note on the “risky” factors. One of the main reasons why we thought the “risky” factors weren’t set up to outperform was because the broader market had not yet seen a meaningful drawdown. Given the drawdown we saw this quarter, it’s harder to make the case that these types of stocks won’t start to perform a bit better, but the speed of the rebound has varied quite a lot in the past and we’re not coming off a larger drawdown like post 2000-2002, 2008-2009, or Mar 2020 that triggered the most violent snapbacks.

Tyler Durden Sun, 04/03/2022 – 22:00



