

The Fed’s Problem: “It’s All About The Money”
By Joseph Carson, former CIO of Alliance Bernstein
The Fed has a problem. It’s in the business of creating money, but it formulates monetary policy without regard to money itself. So in times when its policy decisions produced a record surge in broad money, policymakers are not attentive or alerted to the negative (inflation) consequences.
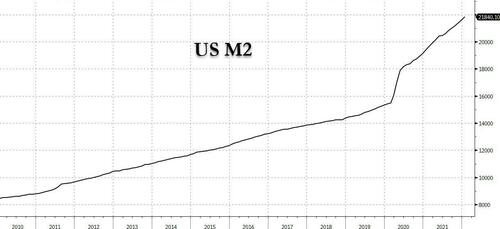
From February 2020 to the end of 2021, broad money increased by $6.5 trillion or over 40%. That increase over less than two years is roughly equivalent to the rise over the previous ten years. Yet, policymakers who have long argued that “inflation is always and everywhere a monetary phenomenon” called the surge in inflation transitory, owing to supply bottlenecks. Had policymakers still recognized money as a potential source of inflation, it would not be in the pickle that they find themselves today.
Policymakers now face the unprecedented challenge of dealing with consumer and producer inflation and elevated asset prices (possibly bubbles.) Policymakers’ record on reversing inflation cycles and recognizing asset bubbles is lousy. Policy adjustments have always been late (except for Greenspan’s 1994 preemptive strike), resulting in awful economic and financial outcomes, some much worse than others.
As bad as policy decisions were in the past year, it is reckless that policymakers are still easing policy today. Publicly saying the monetary policy is “wrong-footed” but not doing anything until the next policy meeting, a month away, is like saying we want the fire to burn some more before being compelled to distinguish it.
Before the preemptive strike against emerging inflation pressures in 1994, Fed Chair Alan Greenspan stated in his semi-annual monetary policy testimony, ” if the Federal Reserve waits until actual inflation worsens, they would have waited far too long.” It’s too late to use Mr. Greenspan’s playbook, but policymakers still need to act swiftly. Some policymakers have argued that only a modest adjustment in official rates is needed because of well-anchored inflation expectations. That is short-sighted and wrong. Actual or realized inflation leads to changes in inflation expectations, not the other way around. Persistent inflation will increase inflation expectations over time.
Several decades ago, the Bureau of Economic Analysis (BEA) created the monetary and financial flow index (MFF). It consisted of the growth in broad money (adjusted for inflation), change in business and consumer credit, and liquid assets. BEA stopped publishing this series in the early 1990s, and I recreated the series with assistance from BEA, plus updating the series for new financial instruments, such as new flows into bond and equity funds.
The MFF index was a helpful gauge to predict the peaks and troughs of economic growth cycles and pinpoint excess liquidity situations. The MFF index signaled excessive liquidity growth (i.e., well above GDP) before the dot.com and housing bubbles. The primary source was explosive private sector credit growth and robust gains in liquid assets.
Over the past year, growth in the MMF index has been more than twice that of dot.com and housing bubbles, owing to record growth in broad money and bank credit. Too much liquidity is the fuel for inflation.
The Fed started this inflation fire by creating too much money. Now, it has to produce less. In January 2022, broad money is up roughly 14% in the past year, down from 25% a year earlier, but still far too fast to kill the inflation dragon. Policymakers have to curtail money growth to a rate well below nominal GDP. That will require a substantial increase in official rates and a sizeable shrinkage in the balance sheet.
Removal of liquidity will appear in asset prices, financial ones before tangible, long before it shows up in conventional measures of inflation. Mr. Market, the biggest beneficiary of Powell and company liquidity bonanza, will soon cry about too little liquidity. Investors forewarned.
Tyler Durden Wed, 02/23/2022 – 19:00



